The Intersection of Contracts and Corporate Law: Opting Out vs. Immutability

Friday, November 13th, 2026
9:00 AM - 4:00 AM

Add to Calendar: Add to Calendar: 2026-11-13 09:00:00 2026-11-13 04:00:00 The Intersection of Contracts and Corporate Law: Opting Out vs. Immutability Event Description We will examine the fundamental question of how much freedom parties should have to opt out of default rules, and which rules should remain immutable to protect essential policy interests and vulnerable stakeholders.We are honored to have Professor Gabriel Rauterberg (University of Michigan Law School) and Professor Sarath Sanga (Yale Law School and Co-Director of the Center for the Study of Corporate Law) joining us as keynote speakers for this event.Reading MaterialsAbstract:Unifying the Law of Corporate ContractingIncreasingly, shareholder agreements play a central role in how corporations shape their governance. They have occupied a prominent place in the jurisprudence and legislative amendments of the last decade. We suggest that the “law of shareholder agreements” is in a state of near-incoherency. This results from the collision of two widely different paradigms for how the law should regulate how corporations opt out from fundamental rules of corporate law. They are both reflected in the law governing shareholder agreements, but one is a product of case law and the other of legislative amendment. When it comes to individual shareholders’ ability to alter rules by contracting among themselves, the governing law comes from Delaware’s courts in Manti and New Enterprise. When it comes to the board’s ability to contract with a powerful shareholder, the governing law comes from Section 122(18). The first approach reflects a carefully structured set of demands for the quality of negotiation; it focuses on bargaining process. The second approach reflects a minimalist approach to process and reliance on fiduciary scrutiny of opt out, instead. It might be thought that however philosophically different these approaches might be, each safely occupies its own arena. But that is not a stable equilibrium. The problem is that contract terms among shareholders or between a shareholder and the board—what you might call horizontal or vertical shareholder contracting—are often functional substitutes. In the end, courts must decide how to govern shareholder agreements through a unified paradigm. We suggest that New Enterprise offers the better route, and that Delaware retreat from Section 122(18). In the midst of a clear race-to-the-bottom dynamic, Delaware can gain market share by staking out principled ground.Unifying the Law of Corporate ContractingIncreasingly, shareholder agreements play a central role in how corporations shape their governance. They have occupied a prominent place in the jurisprudence and legislative amendments of the last decade. We suggest that the “law of shareholder agreements” is in a state of near-incoherency. This results from the collision of two widely different paradigms for how the law should regulate how corporations opt out from fundamental rules of corporate law. They are both reflected in the law governing shareholder agreements, but one is a product of case law and the other of legislative amendment. When it comes to individual shareholders’ ability to alter rules by contracting among themselves, the governing law comes from Delaware’s courts in Manti and New Enterprise. When it comes to the board’s ability to contract with a powerful shareholder, the governing law comes from Section 122(18). The first approach reflects a carefully structured set of demands for the quality of negotiation; it focuses on bargaining process. The second approach reflects a minimalist approach to process and reliance on fiduciary scrutiny of opt out, instead. It might be thought that however philosophically different these approaches might be, each safely occupies its own arena. But that is not a stable equilibrium. The problem is that contract terms among shareholders or between a shareholder and the board—what you might call horizontal or vertical shareholder contracting—are often functional substitutes. In the end, courts must decide how to govern shareholder agreements through a unified paradigm. We suggest that New Enterprise offers the better route, and that Delaware retreat from Section 122(18). In the midst of a clear race-to-the-bottom dynamic, Delaware can gain market share by staking out principled ground. Moot Courtroom - School of Law School of Law School of Law America/New_York public

George A. Leet Business Law Symposium

4.5 hours of CLE credit, pending approval

Event Description

We will examine the fundamental question of how much freedom parties should have to opt out of default rules, and which rules should remain immutable to protect essential policy interests and vulnerable stakeholders.

We are honored to have Professor Gabriel Rauterberg (University of Michigan Law School) and Professor Sarath Sanga (Yale Law School and Co-Director of the Center for the Study of Corporate Law) joining us as keynote speakers for this event.

Reading Materials


Abstract:

Unifying the Law of Corporate Contracting

Increasingly, shareholder agreements play a central role in how corporations shape their governance. They have occupied a prominent place in the jurisprudence and legislative amendments of the last decade. We suggest that the “law of shareholder agreements” is in a state of near-incoherency. This results from the collision of two widely different paradigms for how the law should regulate how corporations opt out from fundamental rules of corporate law. They are both reflected in the law governing shareholder agreements, but one is a product of case law and the other of legislative amendment. When it comes to individual shareholders’ ability to alter rules by contracting among themselves, the governing law comes from Delaware’s courts in Manti and New Enterprise. When it comes to the board’s ability to contract with a powerful shareholder, the governing law comes from Section 122(18). The first approach reflects a carefully structured set of demands for the quality of negotiation; it focuses on bargaining process. The second approach reflects a minimalist approach to process and reliance on fiduciary scrutiny of opt out, instead. It might be thought that however philosophically different these approaches might be, each safely occupies its own arena. But that is not a stable equilibrium. The problem is that contract terms among shareholders or between a shareholder and the board—what you might call horizontal or vertical shareholder contracting—are often functional substitutes. In the end, courts must decide how to govern shareholder agreements through a unified paradigm. We suggest that New Enterprise offers the better route, and that Delaware retreat from Section 122(18). In the midst of a clear race-to-the-bottom dynamic, Delaware can gain market share by staking out principled ground.

Event Location

Moot Courtroom - School of Law
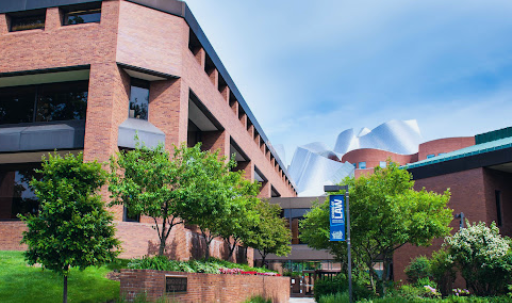
Picture of School of Law -  Gund Hall